BUSINESS FEATURE – Abuja 2026: How IADI summit becomes rallying point for Africa’s financial stability

BUSINESS FEATURE – Abuja 2026: How IADI summit becomes rallying point for Africa’s financial stability
The outcome of the recently concluded Abuja IADI conference shows that deposit insurance has evolved from a little-known technical function into one of the most important pillars of modern financial systems; write our Editor, ONU OKORIE.
In an age where a rumour on social media can trigger a bank run within hours, where digital banking has transformed how millions of Africans save and transact, and where cyber threats have become as significant as traditional financial risks, confidence has emerged as the most valuable currency in the financial system.
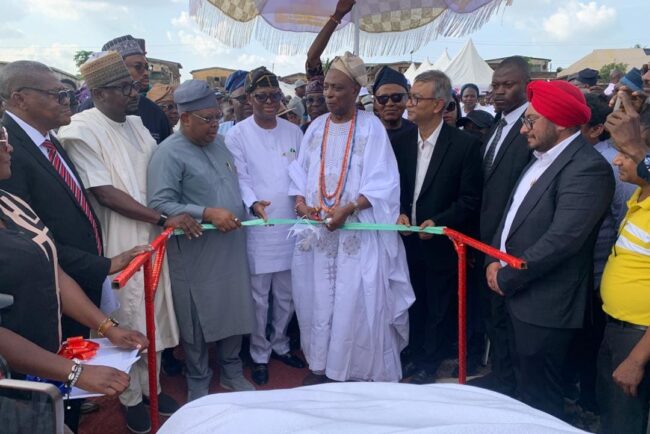
It was against this backdrop that Abuja, Nigeria’s capital city, recently hosted one of the continent’s most significant financial gatherings, the 2026 International Association of Deposit Insurers IADI Africa Regional Committee Annual Meeting and Workshop.
Bringing together deposit insurers, central bankers, financial regulators, policymakers, legislators and development experts from across Africa and beyond, the meeting provided a timely opportunity to examine the future of depositor protection in an increasingly digital and interconnected world.
Far more than a routine annual meeting, the conference underscored Africa’s determination to build resilient financial systems capable of withstanding emerging shocks while protecting millions of depositors whose confidence remains the bedrock of economic growth.
With the theme, “Safeguarding Stability: Public Awareness and Crisis Readiness for a Stronger Future,” the conference successfully shifted the conversation about deposit insurance from a narrow discussion about compensating depositors after bank failures to a broader strategy for safeguarding financial stability, promoting financial inclusion and strengthening economic resilience.
For Nigeria, the event also served as an opportunity to showcase ongoing reforms in its financial sector while reinforcing its growing influence in shaping Africa’s financial stability agenda.
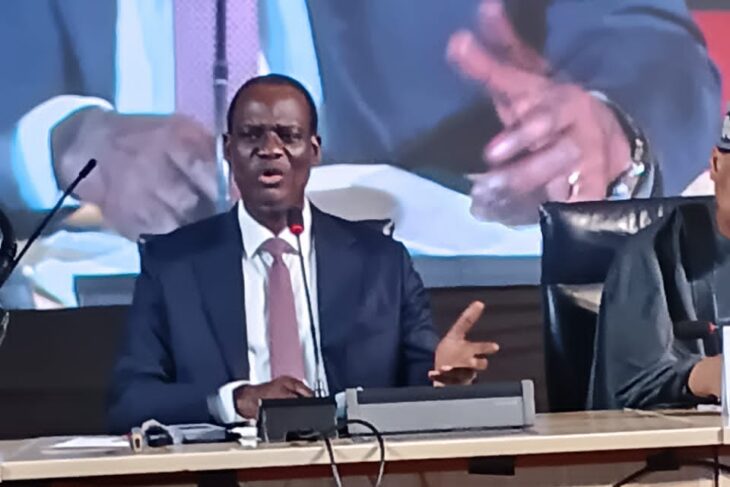
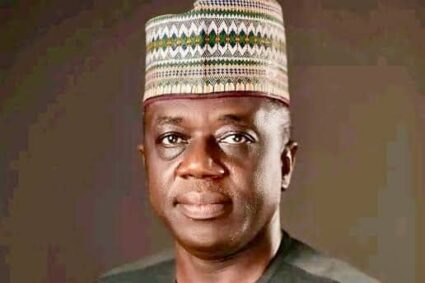
One of the strongest messages to emerge from the conference was delivered by the Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, who argued that no economy can achieve sustainable growth without a stable financial system.
According to him, financial stability extends far beyond banking institutions. It determines whether businesses can obtain credit, whether households feel secure enough to save, whether investors are willing to commit capital and whether governments can successfully implement development programmes.
He noted that while monetary and fiscal policies remain essential tools for economic management, they cannot deliver prosperity if citizens lose confidence in financial institutions.
“The banking sector is the nervous system of the macroeconomy,” the minister observed, explaining that when depositors trust that their money is safe, savings increase, credit expands, businesses invest and economies grow.
That simple but profound message resonated throughout the conference. Participants repeatedly stressed that confidence cannot be legislated into existence; it must be earned through transparency, preparedness, effective regulation and strong institutions.
Historically, deposit insurance was often regarded as a technical mechanism activated only after banks failed. The Abuja conference demonstrated just how dramatically that perception has changed.
Today, deposit insurance has become one of the most important pillars of financial stability. Rather than merely reimbursing depositors after crises, deposit insurers are increasingly expected to prevent panic before it occurs.
Oyedele argued that the revised IADI Core Principles now recognise deposit insurance as a proactive instrument for maintaining confidence in financial systems. This is evolution is especially important in the digital era.
Unlike previous decades when information travelled slowly, today’s financial markets operate in real time. False reports shared online can trigger panic withdrawals within minutes, creating liquidity pressures even for healthy financial institutions.
Participants agreed that public awareness is therefore no longer a public relations exercise but an essential component of financial risk management.
When depositors clearly understand what is protected, how deposit insurance works and how quickly reimbursements can be made, they are less likely to react emotionally during periods of uncertainty.
The Abuja gathering also became an important platform for presenting Nigeria’s ongoing financial and economic reforms to an international audience.
Oyedele outlined several landmark reforms introduced under the administration of President Bola Ahmed Tinubu, describing them as necessary steps towards building a stronger and more resilient economy.
Among the most notable achievements was the successful completion of the Central Bank of Nigeria’s banking sector recapitalisation exercise in March 2026.
Thirty-three of Nigeria’s thirty-seven banks met the revised capital requirements, collectively raising about ₦4.65 trillion in fresh capital, with more than seventy per cent sourced from domestic investors.
The recapitalisation significantly strengthened banks’ capital adequacy ratios beyond international Basel standards while ensuring uninterrupted banking services throughout the exercise.
The minister argued that stronger banks naturally reduce pressure on deposit insurance funds because well-capitalised institutions are better positioned to absorb financial shocks.
Nigeria’s removal from the Financial Action Task Force (FATF) grey list in October 2025 was another milestone highlighted during the conference.
Following two years of coordinated reforms involving the Central Bank, the Nigerian Financial Intelligence Unit, the Economic and Financial Crimes Commission and the Ministry of Justice, Nigeria successfully strengthened its anti-money laundering framework, introduced a beneficial ownership register and improved inter-agency coordination.
According to the minister, international confidence in Nigeria’s financial system has consequently improved, encouraging investors and depositors alike.
For the Nigeria Deposit Insurance Corporation, the conference represented more than hosting responsibilities. It was an opportunity to demonstrate how the institution has evolved over nearly four decades.
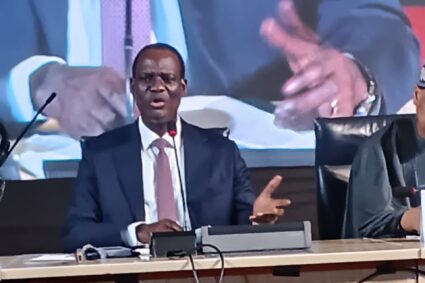
Welcoming delegates, the Managing Director and Chief Executive Officer of NDIC, Mr. Thompson Sunday, described confidence as the most valuable asset in any financial system.
Trust, he noted, requires years to build but can disappear within days if uncertainty takes hold.
That reality explains why modern deposit insurers must extend their responsibilities beyond compensation to include communication, public education, crisis management and institutional preparedness.
Since commencing operations in 1989, the NDIC has consistently upgraded its operational frameworks to match the changing realities of Nigeria’s financial sector.
Today, the Corporation places significant emphasis on depositor reimbursement systems, crisis management capabilities, public awareness campaigns and staff capacity development, all aligned with international best practices.
Sunday also highlighted the growing importance of collaboration among Africa’s deposit insurance institutions.
The Africa Regional Committee, he observed, has become an important platform for peer learning, technical cooperation, policy dialogue and exchange of best practices.
Such cooperation has become increasingly necessary because financial risks no longer respect national boundaries.
Perhaps no speaker captured Africa’s changing financial landscape more comprehensively than IADI Secretary-General Eva Hüpkes.
Her keynote address placed Africa at the centre of global financial innovation.
Sub-Saharan Africa, she noted, now hosts approximately 1.1 billion registered mobile money accounts, accounting for a huge chunk of the world’s total.
The region is also responsible for roughly two-thirds of global mobile money transaction values, estimated at about 1.4 trillion dollars in 2025.
This remarkable growth has transformed financial inclusion across Africa, but it has also created new regulatory challenges.
Traditional deposit insurance systems were designed around conventional commercial banks.
Today’s financial ecosystem includes mobile money platforms, e-money issuers, embedded finance providers, tokenised deposits and even stablecoins.
These innovations blur the traditional boundaries between banking and technology.
According to Hüpkes, deposit insurance systems must therefore evolve rapidly to keep pace with innovation.
The revised 2025 IADI Core Principles respond to this reality by adopting a functional approach that focuses on financial activities rather than institutional labels.
This allows regulators greater flexibility in determining which financial products and institutions should receive deposit insurance protection.
One of the recurring themes throughout the conference was the importance of communication.
Several speakers warned that misinformation has become one of the greatest threats to financial stability.
During periods of uncertainty, rumours often spread much faster than official information.
Without adequate public understanding of deposit insurance, depositors may respond irrationally by withdrawing funds from otherwise healthy financial institutions.
For this reason, participants argued that public awareness campaigns must become continuous rather than reactive.
Deposit insurers should regularly educate citizens about coverage limits, reimbursement procedures and the overall purpose of deposit insurance.
Such education, delegates agreed, is particularly important in rural communities, among small businesses and within underserved populations where financial literacy remains relatively low.
If public awareness represents the first line of defence, crisis preparedness constitutes the second.
The conference devoted considerable attention to lessons from recent global banking disturbances.
The banking turmoil of 2023 demonstrated how quickly financial crises can spread across borders in an interconnected digital economy.
Technology now enables depositors to move billions of dollars within hours.
Cyber attacks, artificial intelligence-generated misinformation and operational disruptions have become major sources of financial instability.
Consequently, delegates stressed that preparedness must become a permanent institutional culture rather than an emergency response.
This includes maintaining robust operational systems, accurate depositor databases, business continuity arrangements, cybersecurity infrastructure and coordinated communication protocols among financial safety-net institutions.
The revised IADI standards now establish seven working days as the international benchmark for reimbursing insured depositors, while encouraging more advanced systems to target reimbursements within three days.
Another major outcome of the Abuja conference was the renewed emphasis on institutional cooperation.
Financial stability, participants agreed, can no longer be delivered by individual organisations acting independently.
Instead, central banks, ministries of finance, deposit insurers, financial supervisors, legislatures and resolution authorities must function as an integrated financial safety net.
Joint crisis simulations, information sharing, memoranda of understanding and coordinated communication strategies were identified as essential tools for maintaining confidence during periods of stress.
This collaborative approach has become even more important as African banking groups continue expanding across national borders.
The conference also recognised the critical role of lawmakers in strengthening financial systems.
Chairman of the Senate Committee on Banking, Insurance and Other Financial Institutions, Senator Mukhail Adetokunbo Abiru, reaffirmed the National Assembly’s commitment to supporting reforms that enhance depositor protection and financial stability.
He emphasised that responsive legislation, effective oversight and sustained collaboration with financial regulators remain essential for protecting depositors in an increasingly complex financial environment.
According to the senator, stronger legal frameworks will complement the efforts of regulators while promoting sustainable economic growth.
Beyond the technical discussions, the successful hosting of the conference significantly enhanced Nigeria’s standing within Africa’s financial community.
The presence of senior policymakers and international experts demonstrated confidence in Nigeria’s institutions and reflected the country’s growing leadership in regional financial policy.
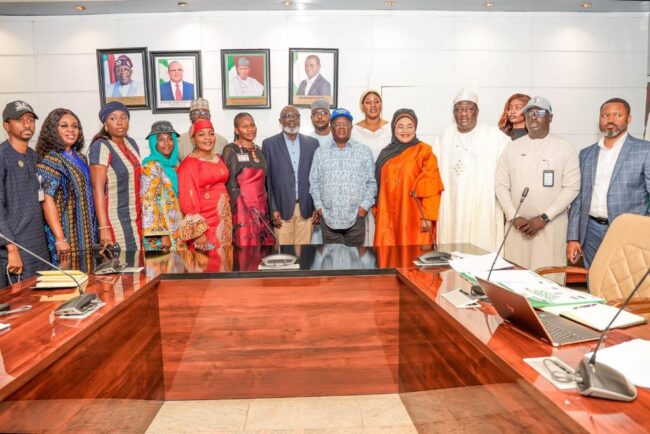
The NDIC, working closely with the Federal Ministry of Finance, the Central Bank of Nigeria and other members of the Financial Services Regulation Coordinating Committee, showcased Nigeria’s commitment to maintaining financial stability through coordinated institutional action.
For many delegates, Abuja demonstrated that Africa possesses both the expertise and institutional capacity to shape global discussions on deposit insurance rather than merely adopting international standards.
As delegates concluded their deliberations, one message stood above all others: financial stability begins with public confidence.
In an era of digital banking, artificial intelligence and rapidly evolving financial technologies, maintaining that confidence will require continuous innovation, stronger institutions, effective communication and unprecedented cooperation among financial safety-net participants.
Its success lay not only in the quality of the discussions but also in its ability to bring together governments, regulators, lawmakers and international experts around a shared objective—building resilient financial systems that protect depositors, inspire investor confidence and support inclusive economic growth.
For Nigeria, hosting the 2026 IADI Africa Regional Committee Annual Meeting and Workshop reinforced the country’s reputation as a leader in financial sector reform and regional cooperation. For Africa, it marked another important step towards creating stronger financial safety nets capable of supporting the continent’s economic transformation.
Ultimately, the enduring legacy of the Abuja meeting will be measured not by the resolutions adopted, but by how effectively its recommendations are translated into stronger institutions, better-informed citizens and financial systems resilient enough to withstand the uncertainties of an increasingly interconnected world.