Fiscal-Monetary synergy, imperative for Nigeria’s economic development

Fiscal-Monetary synergy, imperative for Nigeria’s economic development
By Onu Okorie
As the Federal Government and the Central Bank of Nigeria formalise a framework for closer coordination, the bigger question is whether fiscal discipline and monetary stability can finally reinforce each other strongly enough to lower inflation, reduce the cost of capital, strengthen the naira and translate macroeconomic reforms into better living conditions for households and businesses.
Nigeria’s economic management has traditionally involved two powerful institutions pursuing different but interconnected objectives: the Federal Ministry of Finance, representing the fiscal authority, and the Central Bank of Nigeria (CBN), the monetary authority.
The distinction is important.
But so is the connection.
A government can increase spending, alter taxes, borrow to finance its budget and invest in infrastructure, agriculture or social programmes. At the same time, the central bank can adjust interest rates, regulate liquidity, manage monetary conditions and influence the foreign exchange market.
Each institution has a different mandate. Yet both ultimately operate within the same economy.
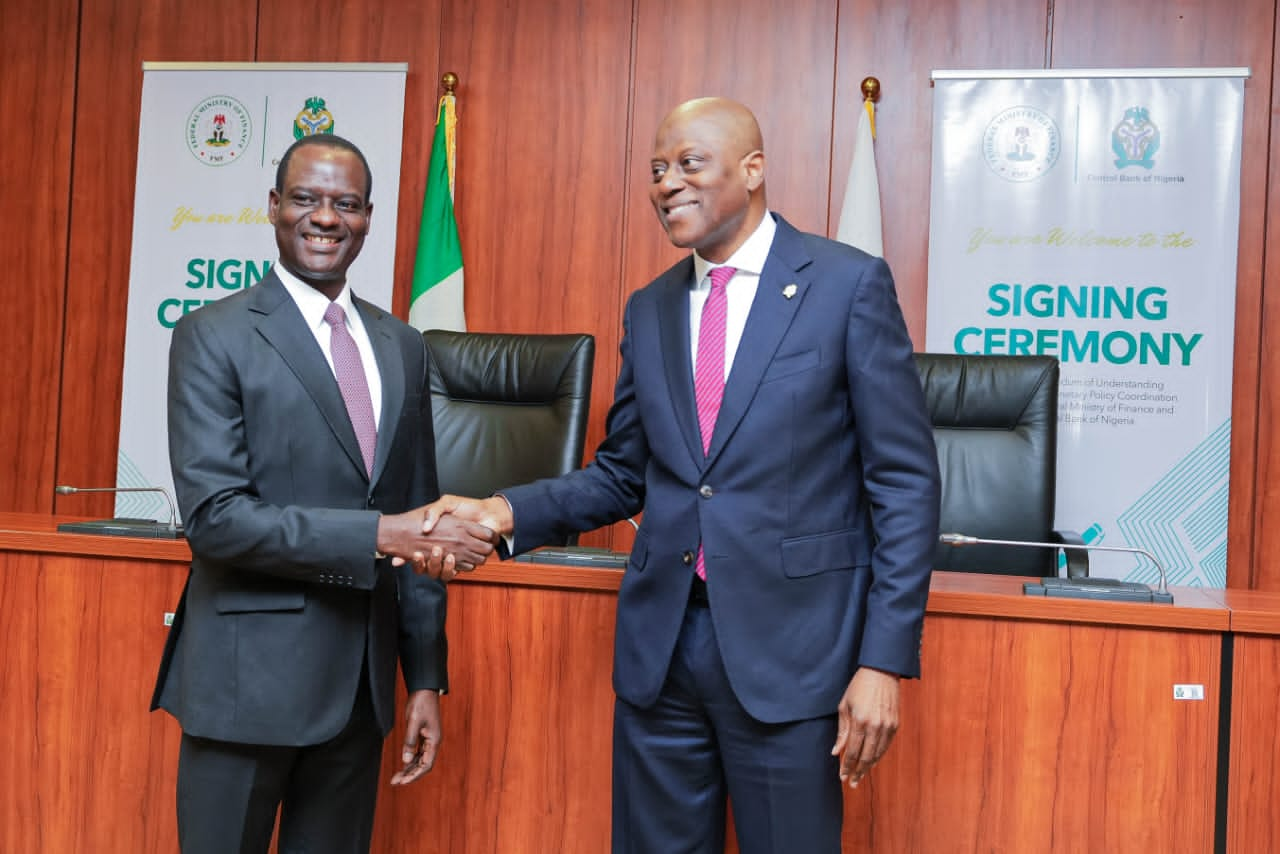
That reality explains the significance of the new Memorandum of Understanding between the Federal Ministry of Finance and the CBN to institutionalise closer coordination of fiscal and monetary policies.
Finance Minister and Coordinating Minister of the Economy, Taiwo Oyedele, captured the central issue when he said: “Nigeria has one economy. Fiscal policy cannot succeed without price stability; monetary policy cannot deliver price stability if fiscal policy pulls in the opposite direction.”
The new framework is therefore more than an administrative agreement. It represents an attempt to ensure that the two major arms of economic management do not unintentionally work against each other.
Fiscal authority versus monetary authority
The fiscal authority is principally concerned with government revenue, taxation, public expenditure, borrowing and debt management. In Nigeria, the Federal Ministry of Finance is at the centre of fiscal policy, working with other government institutions on the budget, taxation, government financing and economic reforms.
Fiscal policy determines how government raises money and how it spends that money.
When government increases productive expenditure on roads, power, irrigation, ports, education or healthcare, it can stimulate economic activity, create employment and improve the productive capacity of the economy.
But fiscal policy can also create problems if poorly managed. Excessive borrowing, inefficient spending or persistent deficits can increase government financing requirements, put pressure on interest rates and crowd out private-sector borrowing.
The monetary authority, on the other hand, is the CBN. Its responsibilities include maintaining price and monetary stability, influencing liquidity and interest rates, safeguarding the financial system and managing monetary conditions.
One of its most visible tools is the Monetary Policy Rate, or MPR.
As of September 20, 2026, the CBN’s MPR stands at 26.5 per cent, following the July decision of the Monetary Policy Committee to retain the rate.
The high policy rate illustrates the difficult balance confronting monetary authorities: controlling inflation and protecting macroeconomic stability while avoiding financial conditions so tight that businesses struggle to obtain affordable credit.
Why coordination matters
The relationship between the two authorities becomes clearer when government borrowing is considered.
When the Federal Government borrows heavily, it competes for funds in the financial system. This can influence market interest rates and the cost of servicing government debt. High borrowing costs can, in turn, make credit more expensive for businesses.
At the same time, monetary policy affects government finances. Higher interest rates increase the cost of servicing domestic debt and can make financing government programmes more expensive.
The exchange rate presents another connection.
A weaker naira can increase the cost of imported fuel, machinery, raw materials, medicines and food inputs. Those costs can eventually reach consumers through higher prices.
The CBN can influence monetary and foreign-exchange conditions, but it cannot build roads from farms to markets, increase agricultural yields or eliminate logistical bottlenecks.
That is where fiscal policy becomes essential.
The new framework recognises precisely this interaction, with the Finance Ministry and CBN agreeing to improve information sharing on cash positions, financing plans, credit growth and foreign exchange flows, while aligning macroeconomic assumptions and forecasts.
Nigeria’s macroeconomic picture
Nigeria enters this new phase with some indicators showing improvement, although significant pressures remain.
The latest National Bureau of Statistics data put headline inflation at 15.39 per cent in August 2026, compared with 15.43 per cent in July. Core inflation was 13.29 per cent, while food inflation stood at 19.57 per cent.
The decline in headline inflation represents a substantial improvement from the much higher rates recorded during the recent inflationary episode. But the level of food inflation shows why the average Nigerian may not immediately feel the full benefit of headline disinflation.
Food prices are particularly important because low-income households devote a large share of their income to food.
The CBN’s current 26.5 per cent MPR also shows that monetary conditions remain relatively tight. The July MPC retained the rate while pointing to improving economic activity, foreign-exchange stability and expected improvement in food supply as factors that could support further disinflation.
Proshare
The exchange-rate picture has also improved compared with the period of extreme volatility that followed the 2023 foreign-exchange reforms.
On September 18, the naira traded at about ₦1,331.20/$1 in the Nigerian Autonomous Foreign Exchange Market (NAFEM), according to market data reported that day.
Business Post Nigeria
Foreign reserves have simultaneously strengthened. CBN data showed gross reserves at $54.61 billion as of September 14, 2026, up from $41.84 billion a year earlier.
The macro economy versus the micro economy
This distinction is crucial. The macroeconomy looks at the economy as a whole: inflation, GDP growth, unemployment, interest rates, exchange rates, government debt, fiscal deficit, money supply and balance of payments.
At that level, Nigeria has recorded several positive developments. Inflation has moderated, the naira has become more stable, foreign reserves have increased and the authorities are seeking to attract longer-term investment.
But the microeconomic picture concerns what is happening to individual households and businesses.
For a small manufacturer, the key questions are different:
How much does it cost to borrow?
How much is diesel?
How reliable is electricity?
How much does it cost to transport raw materials?
Can the business obtain foreign exchange?
How much does it pay workers?
Can consumers afford its products?
This explains why an economy can show improving macroeconomic indicators while households and businesses continue to experience considerable pressure.
The transmission from macroeconomic stability to household welfare takes time.
A stable exchange rate can eventually reduce imported inflation. Lower inflation can improve real incomes. Greater certainty can encourage investment. Investment can create jobs and expand production.
But those benefits depend on the real economy responding.
The case for fiscal policy
This is where fiscal policy becomes particularly important. Monetary policy can restrain excessive demand by making money more expensive. But Nigeria’s inflation problem is not exclusively a demand problem.
Some of the country’s inflationary pressures are structural.
Food production is affected by insecurity, weather conditions, irrigation gaps, storage limitations and inadequate farm-to-market infrastructure.
Manufacturers face energy and logistics costs.
Businesses that depend on imported inputs remain exposed to exchange-rate movements.
This means fiscal intervention must focus on increasing supply and reducing the cost of production.
Oyedele has already identified some of these areas, including strengthening grain reserves, improving agricultural yields and irrigation, building climate resilience and addressing farm-to-market infrastructure.
Such measures can complement monetary policy.
If food supply increases, food-price pressures can ease without the CBN having to rely exclusively on higher interest rates.
If transport infrastructure improves, logistics costs can fall.
If electricity supply becomes more reliable, manufacturers can reduce dependence on expensive alternative energy.
If ports become more efficient, import and export costs can decline.
If government spending is redirected towards productive infrastructure rather than consumption, its economic multiplier can become stronger.
Fiscal policy should be about quality, not simply quantity
The important question is not necessarily whether government should spend more.
It is what government spends on, how efficiently it spends and how it finances that spending.
A government could increase expenditure without significantly expanding productive capacity if resources are lost through inefficiency, poorly targeted subsidies or unproductive projects.
Conversely, well-designed public investment can raise the economy’s productive potential.
Infrastructure is a good example.
A new road connecting farmers to markets can reduce transportation costs, cut post-harvest losses and increase the income of producers.
Irrigation can increase agricultural output beyond dependence on rainfall.
Industrial infrastructure can lower production costs.
Digital infrastructure can reduce transaction costs and improve access to financial services.
These are fiscal interventions that can eventually help monetary policy by addressing supply-side inflation.
The subsidy question
The Finance Minister has ruled out a return to fuel subsidy, arguing that it would place additional pressure on public finances and the naira.
That position illustrates another dimension of fiscal-monetary interaction.
A large subsidy can provide short-term relief to consumers but create a significant fiscal burden if the government must finance it through borrowing or reduced spending elsewhere.
The alternative is to use fiscal resources to address the underlying cost structure of the economy—transport, energy, food production and public infrastructure—while protecting vulnerable households through targeted interventions. The policy challenge is therefore not simply to remove or retain subsidies. It is to ensure that fiscal savings translate into productive investment and targeted social protection.
What other countries can teach Nigeria
International experience shows that fiscal and monetary policy can be mutually reinforcing when their objectives are clearly defined and institutional responsibilities are respected.
Japan provides a particularly relevant example.
In January 2013, the Japanese government and the Bank of Japan issued a joint statement committing to stronger policy coordination to overcome deflation and achieve sustainable economic growth with price stability.
The Bank adopted a 2 per cent price-stability target and pursued monetary easing, while the government committed to growth-enhancing measures and sustainable fiscal management.
The Japanese experience also demonstrates why coordination does not mean sacrificing central-bank independence. The Bank retained responsibility for monetary policy, while the government remained responsible for fiscal and structural policies.
Another example came during the 2008–09 global financial crisis in the United States. Fiscal stimulus from government was combined with aggressive monetary and financial interventions by the Federal Reserve. An IMF-published assessment concluded that the unusually strong combination of fiscal and monetary responses helped the U.S. economy recover from the severe recession, although individual policy measures remained subject to debate.
The lesson for Nigeria is not to copy another country’s policy mechanically. Economic structures differ.
The lesson is that monetary and fiscal authorities can achieve more when their actions are designed around a common understanding of the economic problem.
The danger of working at cross-purposes
Imagine the CBN tightening monetary policy to reduce inflation while government simultaneously injects large amounts of poorly targeted spending into an economy already facing supply constraints.
The two policies can pull in opposite directions.
Similarly, if the CBN is trying to stabilise the exchange rate while fiscal policy creates large unplanned foreign-exchange demand, the monetary authority may face additional pressure.
Conversely, if monetary policy remains extremely tight while fiscal policy successfully expands food production, infrastructure and domestic manufacturing, the eventual reduction in inflationary pressures could create room for monetary conditions to become less restrictive.
This is why information sharing matters.
The new framework’s emphasis on common forecasts, cash positions, financing plans and liquidity conditions could help both institutions see the same economy before making decisions.
From macro stability to the kitchen table
Ultimately, the success of the new fiscal-monetary coordination framework should not be measured only by whether inflation falls or reserves rise.
The bigger test is whether macroeconomic stability begins to translate into improvements in everyday economic life.
For households, that means more predictable food prices, stronger purchasing power and employment opportunities.
For businesses, it means lower financing costs over time, reliable infrastructure, predictable taxes, better access to foreign exchange and a regulatory environment that encourages investment.
For government, it means lower financing pressure and greater fiscal space to invest in productive sectors.
And for investors, it means policy consistency.
This is particularly important as Nigeria seeks to move from short-term portfolio inflows towards what Oyedele described as “patient capital”—investment in factories, infrastructure, technology and jobs.
The road ahead
The new agreement between the Ministry of Finance and the CBN comes at a point when Nigeria’s economy is showing signs of greater stability but remains exposed to inflation, high interest rates, exchange-rate risks, infrastructure constraints and weak purchasing power in parts of the economy.