FG determined to ensure economic reforms benefit ordinary citizens -Oyedele

FG determined to ensure economic reforms benefit ordinary citizens -Oyedele
By Onu Okorie
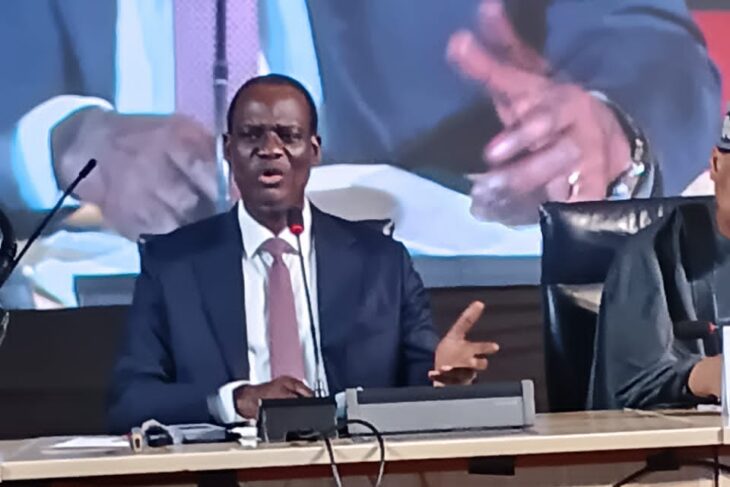
Minister of Finance and Coordinating Minister of the Economy, Taiwo Oyedele, has said that while Nigeria’s key economic indicators are moving in the right direction, the Federal Government is determined to ensure that the benefits of ongoing reforms are reflected in the daily lives of ordinary citizens through improved incomes, reduced poverty and lower inequality.
Speaking at a conference in Lagos on Thursday, Oyedele argued that underlying economic indicators were showing encouraging signs, citing easing inflation, a more efficient foreign exchange market and renewed investor confidence. However, he stressed that macroeconomic stability alone would not be enough to convince Nigerians that the reforms were working.
To address this, the minister announced that the Ministry of Finance plans to begin publishing a set of indicators that will track poverty, income growth and inequality as part of efforts to measure what he described as “shared prosperity.”
According to Oyedele, the proposed scorecard will focus on three major benchmarks: reducing multidimensional poverty, increasing real income per capita and narrowing income inequality.
He explained that President Bola Tinubu’s administration wants to demonstrate that its economic reforms are translating into tangible improvements in the welfare of ordinary Nigerians rather than remaining confined to macroeconomic statistics.
The proposed scorecard is expected to respond to one of the strongest criticisms of the administration’s reform agenda—that gains recorded in government revenue, foreign exchange liquidity and investor confidence have yet to translate into meaningful relief for households battling rising food prices, transport costs and the high cost of living.
The announcement comes as the Federal Government seeks to consolidate support for reforms introduced in 2023, particularly the removal of fuel subsidy and the liberalisation of the foreign exchange market.
Although the reforms received praise from international financial institutions and investors for restoring macroeconomic stability, they also triggered a sharp rise in inflation and living costs, increasing economic hardship for many Nigerians.
The International Monetary Fund noted in June that while Nigeria’s reforms had strengthened investor confidence and improved overall economic stability, an estimated 63 per cent of the country’s roughly 200 million people remained in poverty, with millions also facing food insecurity.
The reform programme has equally attracted criticism over concerns about corruption and allegations of unbudgeted government expenditure, raising questions about whether citizens’ sacrifices have been matched by prudent fiscal management.
Oyedele said the Ministry of Finance would be responsible for compiling and publishing the new scorecard but did not disclose when the first report would be released or how frequently it would be updated.
Meanwhile, Governor of the Central Bank of Nigeria, Olayemi Cardoso, signalled that monetary authorities are not in a hurry to begin cutting interest rates despite the steady moderation in inflation.
Speaking at the same event, Cardoso said Nigeria’s gradual slowdown in inflation had created room for future rate cuts, but warned that global geopolitical developments and other external shocks had complicated the outlook.
Investors have increasingly anticipated the beginning of a monetary easing cycle after inflation slowed for several consecutive months. However, the CBN governor maintained that policymakers would remain cautious.
“There were 11 months of continuous disinflation,” Cardoso said, noting that the trend had strengthened expectations that interest rates would moderate over time.
He, however, explained that geopolitical tensions, including the conflict involving Iran, disrupted the inflation outlook.
“If not for the fact that we had this, we had projected that going into next year inflation would have been down to very moderate levels,” he said.
Cardoso also defended the Monetary Policy Committee’s decision to retain interest rates at its last meeting despite widespread market expectations of a policy shift.
“We didn’t cut, and believe me, we saw things that most other people didn’t see,” he said.
According to him, future monetary policy decisions will continue to be guided by economic data rather than market expectations.
The CBN governor added that Nigeria’s early implementation of key economic reforms had strengthened the country’s resilience against recent global economic shocks.
“One of the reasons for that is the fact that we had undertaken the reforms a lot earlier. We had resilience and we were able to withstand the shocks,” Cardoso said.
The comments by both economic managers underscore the government’s twin strategy of sustaining macroeconomic reforms while seeking to convince Nigerians that the resulting economic gains will ultimately improve household welfare through lower poverty, higher incomes and greater economic inclusion.