Bussiness feature: Insurance for few: breaking elites perception holding the industry back in Nigeria

Insurance for few: breaking elites perception holding the industry back in Nigeria
With penetration below one percent of GDP and barely three percent of adults covered, Nigeria’s insurance sector faces a paradox — impressive premium growth on paper, near-total invisibility on the ground in this analysis, Onu Okorie asks; “can reform and change of mindset fix the problem decades in the making?
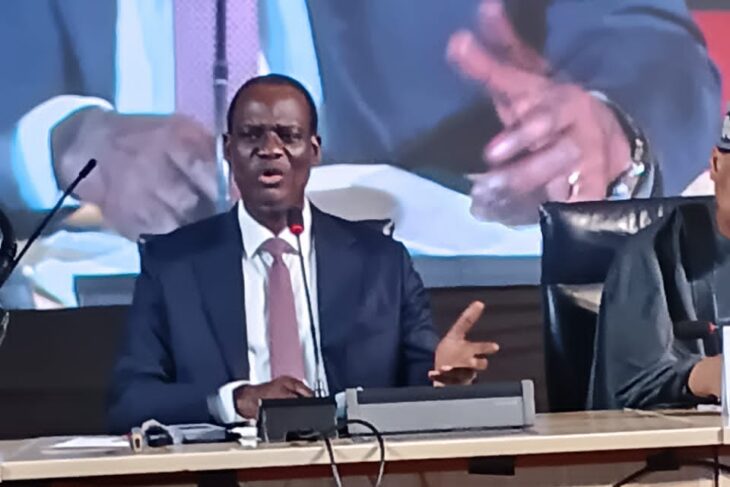
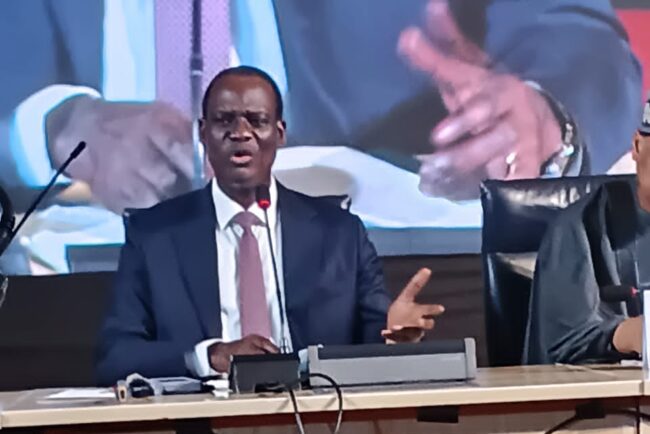
When the Commissioner for Insurance, Mr. Olusegun Ayo Omosehin, took the podium at the opening of Insurance Week 2026, his words carried the weight of an industry that knows its own contradictions too well. “Without awareness, there can be no demand,” he told the gathering. “Without understanding, there can be no trust. And without trust, sustainable growth cannot be achieved.”
It was a candid diagnosis from the top of Nigeria’s insurance regulatory pyramid and the numbers behind it are stark.
Nigeria is home to over 237 million people, the largest population on the African continent and one of the largest economies in the world. Yet fewer than three percent of Nigerian adults carry any form of insurance coverage, and insurance penetration hovers between 0.3 and 0.5 percent of GDP, one of the lowest rates on earth. Comparatively, South Africa posts an insurance penetration rate of 11.3 percent, Namibia 7.4 percent, Morocco 2.1 percent, and Kenya 1.2 percent, while Nigeria, the supposed giant of Africa, lags behind all of them.
The situation at the micro level is even more troubling. According to the 2021 Access to Financial Services in Nigeria Survey by EFInA, only about 2 million Nigerians have any form of insurance coverage. In a comparison of Nigeria with five other African countries, the report found that Nigeria has the highest proportion of uninsured adults. Nigerian businesses fare no better; of 388 businesses sampled by Interpoint Africa in January 2024, a staggering 96.4 percent had no insurance coverage, with business owners saying products were either too expensive or they simply did not know where to begin.
To make the matter words, Nigerian public also ignores mandatory insurance or the kind of insurance policy the law compels. Six types of insurance are legally required in Nigeria, including motor third-party liability. Yet of 12 million vehicles on Nigerian roads, only about 3.4 million are insured, a 72 percent non-compliance rate for something already mandated by law.
Ask an average Nigerian on the streets of Onitsha, Kano, or Mushin about insurance and the response is likely to be a dismissive wave of the hand. Insurance, in the popular imagination, is something for big companies, rich individuals, and multinationals and not for the petty trader, the okada rider, the smallholder farmer, or the artisan.
This perception did not emerge from thin air. It was built over decades of an industry that, consciously or not, designed itself around corporate clients and high-value assets. The bulk of premium income in Nigeria comes from corporate lines such as oil and gas insurance, property, and employer-mandated group life. The average Nigerian consumer is barely in the picture. Insurance density in Nigeria is roughly $7 per person. In South Africa, it is closer to $700.
Commissioner Omosehin acknowledged this structural flaw directly in his Insurance Week address, identifying a damaging perception that insurance companies “only sell what has been produced, rather than producing what can be sold.” This, he noted, is the critical difference between marketing and mere selling and it has cost the industry dearly in public confidence.
The consequence is a sector that, despite its legal and economic mandate, remains psychologically distant from the people it is supposed to serve. Insurance is seen not as an everyday financial tool but as a rarefied product requiring specialized knowledge, formal employment, a bank account, and disposable income that many Nigerians simply do not have.
But beyond affordability and access lies a deeper, more corrosive problem, lack of trust among consumers. The Nigerian insurance industry carries a decades-long reputation for not paying claims. A VIISAUS study in Lagos found that 38 percent of respondents said they simply do not see the need for insurance, while 19 percent cited trust issues and another 21 percent pointed to cost. When people have heard enough stories of insurers collecting premiums and then refusing or delaying payment when something goes wrong, the rational response is to self-insure through savings, family, or community contributions and that is exactly what most Nigerians do.
This is the heart of the elite perception problem. Insurance is not merely seen as expensive, it is seen as a rigged game, one where the rules favour the house. The claims experience, what industry insiders call the “moment of truth,” has too often been a moment of disappointment. Omosehin, in his address, was direct about this: delays, ambiguities, and perceived unfairness in claims settlement “not only erode trust but also weaken confidence in the entire system.”
The irony is that the informal risk-pooling culture has always existed in Nigeria. Esusu, ajo, cooperative societies, these are homegrown insurance systems that communities have trusted for generations. Traditional risk-pooling mechanisms like tontines, which represent the essence of insurance, have existed for generations across Africa. What Africa has lacked is an insurance industry designed around people-based access rather than asset-based protection.m
To be fair to the industry, there are genuine signs of forward movement. The Nigerian insurance industry recorded a 47.3 percent year-on-year growth rate in Gross Premium Written, reaching N2.30 trillion at the close of the fourth quarter of 2025. NAICOM described this as reflecting the “increasing relevance of the sector within Nigeria’s financial ecosystem and a deepening of public confidence in the market.”
Health insurance coverage has also edged upward, with the number of Nigerians holding health insurance rising from 19.2 million in 2024 to 21.7 million in 2025, representing roughly 13 percent of the national population.
But critics urge caution about reading too much into premium growth figures. Industry operators note that insurance penetration remains weak due to low public awareness, widespread mistrust, limited access, and low purchasing power, particularly among households and the informal sector. Premium growth driven largely by oil and gas and corporate accounts does little to change the lived reality of ordinary Nigerians.
Despite regulatory reforms and increased stakeholder collaborations in 2025, only about one percent of Nigerians have embraced insurance, highlighting persistent hurdles in awareness, affordability, and accessibility.
Perhaps it’s to reinvent the insurance industry in Nigeria that the federal government embarked in comprehensive reforms of the sector following the Nigerian Insurance Industry Reform Act signed into law in 2025. Many believe that the Act represents the most ambitious legislative overhaul the sector has seen in over two decades. Omosehin described it as “not merely a legislative update” but “a comprehensive reform framework strategically designed to reposition the Nigerian insurance sector for sustainable growth, enhanced competitiveness, and increased public confidence.”
The Act mandates a digitized insurance value chain, strengthens enforcement, and introduces measures to improve policyholder protection. NAICOM has also issued operational guidelines for insurtech firms, formalizing the regulatory framework for digital insurance providers and promoting competition and innovation.
However, enforcement of compulsory policies such as motor insurance remains a priority, with NIIRA including provisions to fund enforcement agencies to ensure better compliance and collaboration against defaulters.
Technology is also being positioned as a democratizing force. Digital platforms, mobile-first products, and insurtech innovation hold genuine promise for reaching communities that traditional agents and brokers have never served. As one analyst noted, embedded insurance, integrating coverage directly into everyday transactions could finally meet Nigerians where they already are, rather than asking them to seek out an industry they do not yet trust.
The Commissioner’s message at Insurance Week 2026 was ultimately a call to collective accountability. Regulation alone, he conceded, cannot close the gap. Insurers must transition from product-centric to customer-centric models. They must co-design products with communities, simplify documentation, communicate in local languages, and above all pay claims promptly and fairly.
“Trust is not built overnight,” Omosehin said. “It is earned through consistent actions, dependable service, and unwavering integrity. Every policy issued, every claim settled, and every client interaction contributes to the public perception of our industry.”
For Nigeria’s insurance sector, the challenge is not just regulatory or commercial. It is fundamentally one of identity. The industry must decide whether it exists to serve a narrow, wealthy elite or whether it is ready to become what it has always promised to be: a genuine safety net for every Nigerian, regardless of income, location, or social standing.The potential is undeniable. The population is vast, the risks are real, and the appetite for financial security is universal. What remains to be built is the trust to match it.